A low factory quote can make a private-label golf ball program look profitable before setup, landed cost, channel fees, returns, and inventory exposure are counted.
Yes—private label golf balls can be profitable, but only when the program survives five economic gates: Quote → Landed → Contribution → Cash → Reorder. The gap between factory price and selling price is only a starting point; the program must still survive real channel costs, inventory exposure, and the economics of PO #2.
If your product, channel, and target selling price are not yet defined, resolve those launch decisions first. This analysis begins when you already have a proposed SKU, supplier quote, selling channel, and expected price—and need to decide whether the program deserves an OEM PO.
Your commercial test is straightforward: What does the program really cost, what does each dozen contribute, how much cash must you expose before demand is proven, and would you willingly fund PO #2 once forecasts are replaced with actual results?
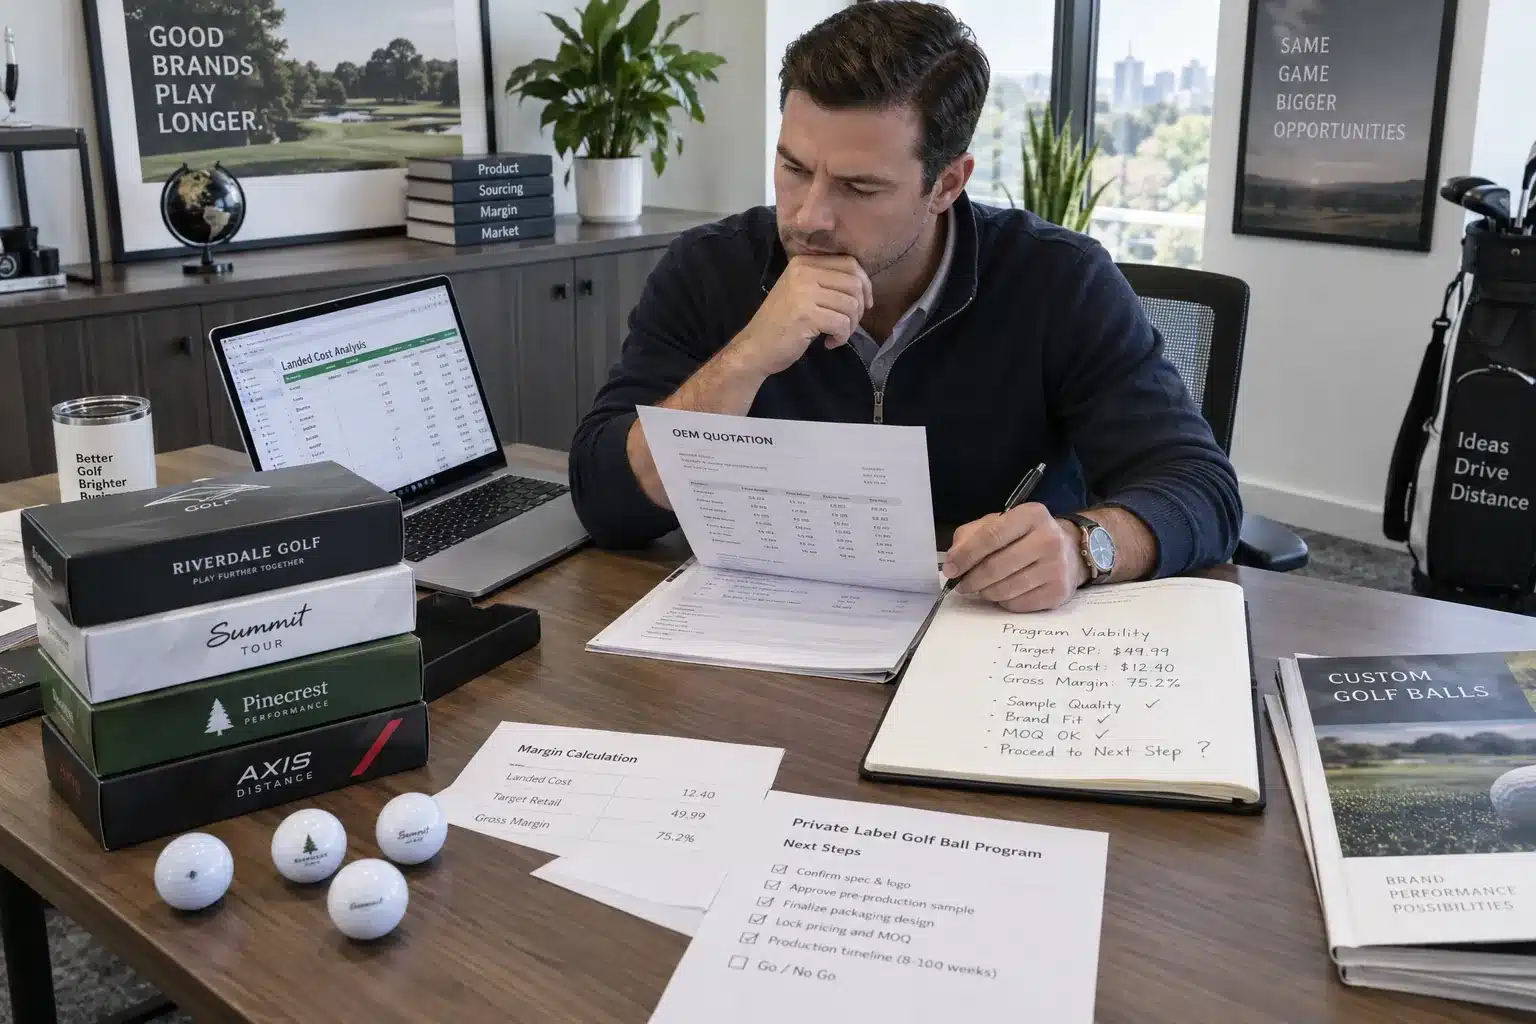
Can this private-label program make money?
Your factory quote can look profitable while the program behind it is economically weak. The difference between supplier price and your intended net selling price is only the beginning of the calculation.
A private-label golf ball program is viable only when the economics survive five gates: quote, landed cost, contribution margin, cash exposure, and reorder. A wide factory-to-selling-price spread is not enough if channel costs, inventory, discounts, returns, or PO #2 consume the margin you expected.
Use one commercial sequence throughout the project:
Quote → Landed → Contribution → Cash → Reorder
Each gate asks a different question.
Quote: What has your supplier actually priced?
Landed: What does the approved product cost when it reaches the point where your business can sell or use it?
Contribution: What remains after the variable costs directly associated with selling each dozen?
Cash: How much capital must you commit before demand is proven?
Reorder: After the first batch produces real sales and cost data, would you willingly fund PO #2?
Those distinctions matter because Factory Quote ≠ Landed Cost, Gross Margin ≠ Contribution Margin, and Unit Cost ≠ Cash Exposure.
| Buyer Decision | Variable to Calculate | What Can Distort It | Evidence to Request | Go/No-Go Action |
|---|---|---|---|---|
| Is the quote complete? | Quoted program cost | Blended charges | Itemized quote | Clarify scope |
| What is the delivered cost? | Landed cost | Freight/duty assumptions | Verified landed basis | Verify input |
| Does each sale contribute? | Contribution | Fees/discounts/returns | Actual channel costs | Approve price |
| How much cash is exposed? | Cash commitment | MOQ/setup/inventory | PO + setup schedule | Cap exposure |
| Is inventory moving? | Sell-through | Slow stock/markdowns | Sales record | Hold or reorder |
| Does PO #2 work? | Reorder economics | New costs/spec changes | Reorder quote | Reorder or stop |
For landed cost, use the commercial basis applicable to the actual shipment. Do not turn an old freight quote or assumed duty rate into a permanent input. If you need to calculate or verify that layer in detail, use the dedicated golf ball landed-cost calculation.
Before PO approval, build a Program Economics Input Sheet containing the quoted scope, landed-cost basis, channel-cost assumptions, inventory commitment, payment schedule, and intended reorder basis.
Your team should be able to reconstruct the economics from source inputs rather than accepting one blended “margin” number.
✔ True — A low factory quote can coexist with a weak business model
The product still has to survive landed cost, channel expenses, inventory exposure, and replenishment economics. Factory price is only the first input.
✘ False — “If gross margin looks attractive, the program is profitable”
Gross margin can look healthy while fulfillment, discounts, returns, replacements, advertising, or slow inventory remove the contribution your business expected.
What does the first order really cost?
PO #1 often carries development and setup costs that may not repeat. If those costs are blended into the unit price, you can misread both first-order profitability and the economics of a later reorder.
First-order economics and reorder economics should be calculated separately. Development, artwork, tooling, print setup, packaging setup, and validation may burden PO #1, while recurring product, decoration, packaging, logistics, fulfillment, returns, and storage determine whether PO #2 still works.
This distinction becomes especially important when comparing an established factory platform with new development.
An approved SKU based on existing tooling, a mature construction, and straightforward decoration may carry fewer first-order development charges. A project requiring new tooling, artwork preparation, packaging development, unusual decoration, or additional validation may put more cost into PO #1.
Neither is automatically better. You need to know which expenses repeat.
Which costs disappear on reorder?
Separate every relevant cost line into three questions:
Does it happen once?
Does it repeat on every unit?
Does it return only when something changes?
| Cost Item | First Order | Reorder | Evidence to Request | Buyer Action |
|---|---|---|---|---|
| Product development | Possible | Conditional | Development scope | Separate NRE |
| Artwork / print setup | Possible | If changed | Setup charge | Record once |
| Tooling | If required | If replaced/changed | Tooling quote | Isolate cost |
| Unit ball cost | Yes | Yes | Per-unit basis | Compare tiers |
| Unit decoration | Yes | Yes | Print-action basis | Calculate recurring |
| Packaging | Yes | Yes if retained | Setup + unit split | Test value |
| Logistics | Yes | Yes | Current freight basis | Requote |
| Fulfillment / channel | After sale | After sale | Actual channel data | Model contribution |
Printing shows why this matters. “Logo included” is not a useful economics category if you cannot tell whether it includes a one-time setup charge, multiple print positions or actions, or a recurring decoration cost on every unit.
A supplier that gives one blended price but cannot separate one-time and recurring costs is a failure signal. Your team cannot tell whether weak PO #1 economics come from development expense or a weak recurring unit model.
Request a Program Economics Quote Pack containing ball cost, printing setup, recurring decoration basis, packaging setup, recurring packaging basis, tooling or NRE where applicable, sampling or validation cost, freight/import basis, reorder unit basis, and excluded items.
Use this request in the RFQ:
Please itemize one-time development and setup charges separately from recurring per-unit product, decoration, packaging, and logistics charges, and state the pricing basis that would apply to a reorder of the approved build.
The commercial requirement can also state:
Supplier shall separate one-time development, tooling, artwork, printing setup, and packaging setup charges from recurring per-unit ball, printing, packaging, and logistics charges so first-order economics and reorder economics can be evaluated independently.
If decoration complexity materially changes setup or recurring cost, move the technical decision to the custom golf ball printing methods and adhesion guide. This page only needs to establish what happens once and what you will pay again.
What is your contribution margin per dozen?
A private label golf ball profit calculation can look attractive when it stops at net selling price minus product cost. That still leaves many of the costs caused by making the sale outside the model.
Contribution per dozen is the dollar amount that remains after net realized revenue is reduced by landed product cost, channel variable costs, and replacement or claim costs. Contribution margin expresses that contribution as a percentage of net realized revenue.
Use:
Contribution per Dozen
= Net Realized Revenue per Dozen
– Landed Product Cost per Dozen
– Channel Variable Costs per Dozen
– Replacement / Claim Costs per Dozen
Net Realized Revenue should already reflect discounts, refunds, and credits, so do not subtract the same revenue reduction twice. Channel Variable Costs can include applicable marketplace fees, fulfillment, payment fees, commissions, and other costs that rise with the sale.
Then calculate:
Contribution Margin %
= Contribution per Dozen ÷ Net Selling Revenue per Dozen × 100
If advertising is directly attributable and material:
Contribution After Ads per Dozen
= Contribution per Dozen
– Actual Attributable Ad Spend per Dozen
This distinction matters because the same golf ball can have very different economics in different channels.
A pro shop may avoid marketplace referral fees while carrying discounts, staff incentives, or shelf-space costs.
A distributor may accept a lower net selling price in exchange for larger or more predictable orders.
A corporate program may avoid consumer advertising but carry presentation, deadline, replacement, or service costs.
An ecommerce program can add platform charges, fulfillment, storage, returns, and attributable advertising.
The product may be identical. The contribution is not.
The U.S. Small Business Administration’s break-even guidance similarly separates selling price, fixed costs, variable costs, and break-even thinking. It does not define the correct golf-ball margin; it supports the discipline of separating cost types before deciding whether a commercial model works.
Amazon is a useful channel example. Its official seller pricing separates selling-plan, referral, fulfillment, and other potential costs. For an actual private-label golf ball SKU, use Amazon’s current fee and revenue estimator with the approved selling price, the fee category assigned to the actual SKU, fulfillment method, package dimensions, and shipping weight rather than inserting a generic FBA cost into your spreadsheet.
Channel economics are SKU-specific. Your contribution model should be too.
Does every custom feature earn its cost?
A recurring custom feature deserves to remain only when the channel can monetize it through price, conversion, presentation, operating need, or stronger reorderability.
In one current Golfara custom-packaging configuration, we priced a retail-ready 12-ball set at about US$1.12, with a 500-set MOQ. That represents about US$560 in packaging commitment for 6,000 balls. At three 6,000-ball replenishment orders per year, repeating the same retail packaging would add about US$1,680 in packaging cost alone, before any additional freight effect. For many facility-use programs, we would instead recommend retaining the custom logo while using bulk export packing—for example, 300 balls per carton—when retail presentation adds little value to the end user.
Those figures describe one current Golfara custom-packaging configuration, not an industry benchmark for custom golf ball packaging.
The lesson is not that retail packaging is wasteful. It is that packaging should earn its cost in the channel where the ball is actually sold or used.
A DTC brand may need a retail-ready box because presentation supports conversion, gifting, reviews, or the selling price.
An indoor facility can face a different equation. If balls move directly from shipment into operating inventory, the logo may still create value while a retail dozen box does little for the end user.
For every recurring customization, ask:
-
Does it help you sell more?
-
Does it help you charge more?
-
Does it reduce a meaningful risk?
-
Does it improve reorderability?
If none applies, treat the feature as a recurring cost that requires commercial justification before repeating it.
Quality also belongs in the economics. Holds, rework, replacements, returns, and complaints can consume contribution even when the original approval sample looked excellent. Do not invent a standard defect allowance; replace your forecast with actual program data once it exists.
If retail presentation does earn its cost, compare the dedicated OEM golf ball packaging options before finalizing the pack-out.
✔ True — Customization can support contribution when the channel monetizes it
Packaging, decoration, or presentation can support price, conversion, brand value, operating needs, or reorderability when the customer or channel actually rewards the feature.
✘ False — “If a feature can be customized, it belongs on every reorder”
A custom feature that customers do not notice, pay for, or operationally require can become a recurring margin leak rather than a brand asset.
How much cash does the pilot actually expose?
A smaller MOQ feels safer because the PO total is lower. But a lower quantity can also increase unit cost, setup allocation, packaging allocation, or freight per dozen.
A lower MOQ can reduce inventory exposure while still producing weak pilot economics. Compare the cash committed to inventory, setup, packaging, freight, receiving, and storage against the contribution the pilot can generate, and favor the most reversible capital commitment—not automatically the lowest unit price.
Use:
**Cash Exposure
= Pilot Inventory Commitment
- One-Time Development / Setup
- Packaging Commitment
- Freight / Import Cash
- Receiving / Storage
– Verified Customer Deposits or Preorders**
Only subtract deposits or preorders that are real, usable in time, and tied to the relevant program. A sales forecast is not cash.
The more useful comparison is:
Pilot Cash Exposure vs. Scaled Unit Economics
rather than:
MOQ A vs. MOQ B
At the pilot stage, prefer reversible inventory commitment over the lowest possible unit cost when the smaller commitment materially protects your ability to change course after real customer evidence.
Your team celebrating a low MOQ without calculating both contribution per dozen and total cash exposure is a failure signal.
What should trigger markdown or reorder?
Define those decisions before inventory arrives.
Set your own:
-
target sell-through window;
-
markdown trigger;
-
dead-stock trigger;
-
reorder trigger;
-
minimum acceptable realized contribution;
-
maximum acceptable return or complaint exposure.
Do not borrow a generic 30-, 60-, or 90-day threshold and present it as a golf-industry standard.
A useful qualitative framework is:
High Contribution + Low Cash Exposure → strongest pilot
High Contribution + High Cash Exposure → demand-risk review
Low Contribution + Low Cash Exposure → learning-focused test
Low Contribution + High Cash Exposure → hold
Slow inventory can also create additional channel costs. Where storage or inventory-age charges apply, update them with current channel data rather than assuming your original model remains valid.
Request a Pilot vs Scale Quote showing pilot quantity, scale quantity, unit cost at each level, setup allocation, packaging commitment, freight basis, and reorder basis. Calculate both cash exposure and contribution per dozen before approving quantity.
If the next question is whether the production run qualifies as a technically valid manufacturing trial, use the valid OEM golf ball pilot guide. This page owns the capital decision; that page owns manufacturing-pilot validity.
Will the reorder still deserve your cash?
PO #1 can sell out and still fail the real commercial test. By the time you consider PO #2, forecast assumptions have become actual selling prices, discounts, returns, freight costs, complaints, advertising spend, and inventory velocity.
PO #2 is the real commercial test: replace forecast selling price, fees, discounts, returns, fulfillment, advertising, freight, and sell-through with realized data, then add current supplier and channel costs. If you would not place the same order again at that realized contribution and cash exposure, PO #1 did not prove the model.
Think in three stages:
Quoted Economics → Realized Economics → Reorder Economics
Quoted Economics contains the assumptions used before committing cash.
Realized Economics replaces those assumptions with actual net revenue, discounts, channel costs, refunds, replacements, attributable advertising, complaint costs where monetizable, and inventory velocity.
Reorder Economics then adds the current supplier quote, current logistics/import basis, current channel costs, actual replenishment quantity, and the exact product, artwork, and packaging revision being priced.
| Reorder Input | First-Order Assumption | Realized Result | What Changed | Buyer Action |
|---|---|---|---|---|
| Net selling price | Forecast | Actual | Discount/promo | Reprice |
| Channel fees | Forecast | Actual | Fee update | Recalculate |
| Returns/replacements | Allowance | Actual | Higher/lower | Update reserve |
| Landed cost | Quote | Actual | Freight/import | Requote |
| Packaging | Approved basis | Actual | Cost/spec change | Review |
| Sell-through | Target | Actual | Faster/slower | Reorder/hold |
| Product/version | Approved | Current | Any change | Confirm/reapprove |
| Contribution | Forecast | Realized | Full variance | Fund or stop |
A first-order margin model has a date. It is not permanent truth.
Even if your factory price stays unchanged, channel fees, freight, promotions, fulfillment, returns, packaging cost, advertising efficiency, or net selling price may move before PO #2.
That is why a program is not commercially validated merely when PO #1 ships. The stronger evidence is that you are still willing to fund PO #2 at the realized margin.
What must stay the same on reorder?
Economics can change because the market changed. They can also change because the product being quoted is no longer exactly the version you approved.
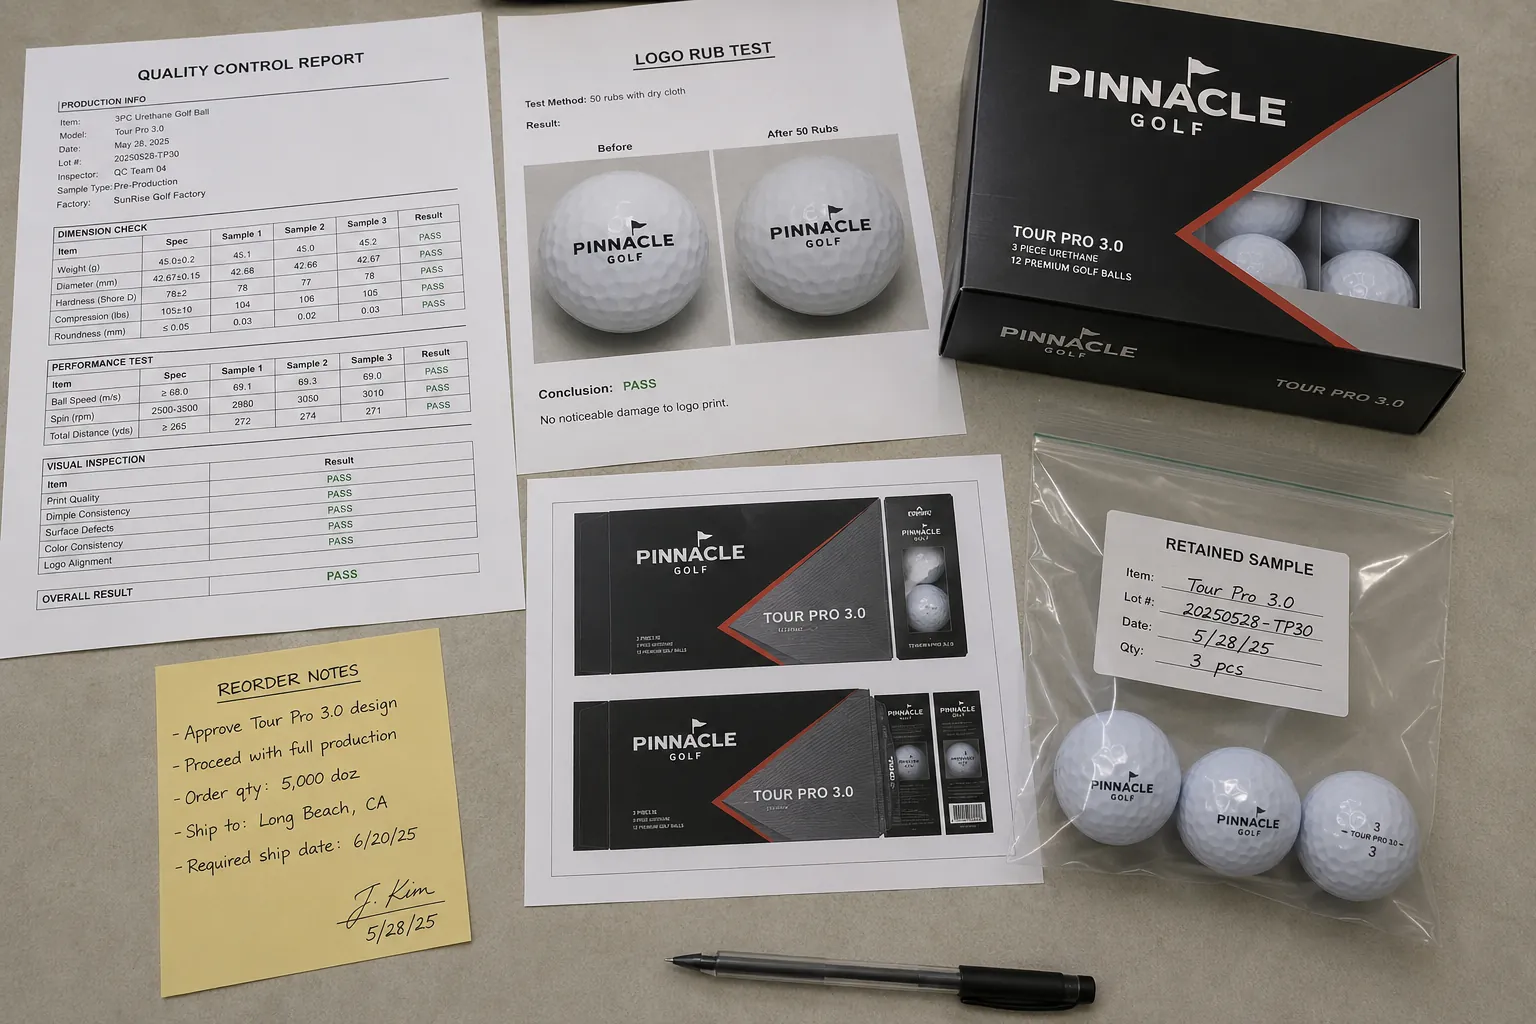
Build a Reorder Reference Pack containing:
-
approved product revision;
-
artwork revision;
-
packaging revision;
-
approved sample or reference;
-
pilot or previous production batch;
-
disclosed changes;
-
current reorder quotation basis.
A reorder quotation that cannot confirm the approved product, artwork, packaging, and pricing basis is a failure signal.
Use this clause:
Any reorder quotation shall identify the approved product, artwork, and packaging revisions used as the pricing basis, and disclose any material, process, print, packaging, or production-route change before buyer approval.
Before PO #2, recalculate contribution using realized data and current supplier/channel inputs. Then ask:
Would we willingly place this PO again at this realized contribution and cash exposure?
If yes, the economics have survived a much stronger test than the original spreadsheet.
If no, additional volume will usually amplify the problem rather than fix the underlying unit economics.
✔ True — The second PO is stronger evidence of commercial viability than the first shipment
The reorder forces forecasts to compete with real selling price, actual costs, returns, inventory velocity, and the supplier’s current commercial basis.
✘ False — “If the first batch sold out, the business model is proven”
A sell-out can still hide heavy discounting, high returns, weak contribution, excessive cash exposure, or replenishment economics that no longer justify another order.
FAQ
Should customer deposits reduce cash exposure?
Yes—when the deposit or preorder is verified, usable before the corresponding inventory commitment, and genuinely reduces the amount of your own capital at risk. Verbal forecasts, expressions of interest, or uncommitted customer demand should not be treated as cash in the model.
Record the confirmed amount, when the funds become usable, and which PO they support. If the customer pays only after your supplier deposit and packaging commitment are already due, that money may improve overall cash flow without reducing your initial funding requirement. Keep those two effects separate.
How should tooling affect first-order margin?
Treat tooling or development as a separate one-time or conditional cost unless it genuinely repeats with every order. Otherwise PO #1 can look artificially weak, or PO #2 can look artificially attractive because nobody documented what would cause the tooling charge to return.
Request the tooling charge separately and identify whether it is tied to the current product revision. Record ownership or usage rights when commercially relevant. If a later revision needs different tooling, update the reorder economics instead of assuming the original NRE treatment still applies.
What if sell-through is good but returns rise?
Fast sell-through does not prove healthy economics if refunds, replacements, complaints, or discounting erode realized contribution. Replace the forecast return allowance with actual return and replacement data before deciding whether the first-order performance justifies another private-label golf ball PO.
Identify whether the problem is product-, packaging-, or channel-related, but keep its economic effect in the model regardless of cause. Revenue is not contribution, and units shipped are not the same as profitable units retained.
Should fixed overhead be inside contribution margin?
Usually no. Keep contribution focused on net realized revenue minus landed product cost and the variable costs caused by the sale; then evaluate fixed overhead separately when you calculate break-even or operating profit. Mixing fixed overhead into per-dozen contribution can make channel comparisons harder to interpret.
Compare its recurring cost with a simpler pack-out, review customer or channel feedback, and include any meaningful freight or cube effect. Keep the retail presentation when it earns its economics. Simplify it when the customer is paying for the ball rather than the box.
How should Amazon fees enter your model?
Use the actual SKU, package dimensions, shipping weight, current fee category, fulfillment method, and Amazon’s live official tools instead of inserting a generic FBA percentage or cost per dozen into your private-label golf ball contribution model.
Start with current Amazon seller pricing, then use the official fee and revenue estimator with the approved sellable configuration. Before PO #2, replace forecast fulfillment, storage, advertising, refunds, returns, and other applicable costs with realized or current data wherever available.
When should a cost change force a reprice?
Reprice when a supplier, logistics, channel, return, fulfillment, or other material cost change pushes contribution below the threshold your program approved. There is no universal private-label golf ball percentage that should automatically trigger a selling-price increase.
Identify which input changed, recalculate contribution per dozen and contribution margin percentage, and test whether the channel can absorb a new price without damaging demand. If revised economics no longer pass your contribution and cash criteria, hold the reorder instead of assuming higher volume will repair the model.
Conclusion
A private-label golf ball program is not proven because the factory quote looks cheap or because the first batch sells. It is proven when Quote → Landed → Contribution → Cash → Reorder still works after forecasts are replaced with real numbers.
If PO #2 still delivers acceptable realized contribution while the approved product, artwork, packaging, and cost basis remain controlled, you have something worth scaling. If it does not, more volume will usually amplify the problem rather than fix it.
Once the economics pass the reorder test, the next decision is how to turn that approved business model into a controlled market launch.
You might also like — How to Launch a Golf Ball Brand with a China OEM